Skip to the article Read this first. This guide shows how to price a dollar-billed software subscription in naira, using the figures I could verify and flagging the ones I could not. It was prepared with AI assistance for research and drafting; Samson Ese is the named author and is responsible for what Daily Reality NG publishes. It is general information, not tax or financial advice, and no software vendor is recommended here. Business and Finance · Software and Subscriptions · Published 27 October 2026 · Rates and rules checked as of October 2026 Business Software in Nigeria: The Naira Costs the Pricing Page Leaves Out Clear promise: you will see which extra costs sit on top of a dollar software price in Nigeria, how large each one is on a worked example, and how to work out your own monthly and annual total before you pay. Who it is for: founders, finance officers and team leads who pay for foreign software with a Nigerian card or account. Home › Business and F...
Get link
Facebook
X
Pinterest
Email
Other Apps
Payroll Software Nigeria 2026: Stop FIRS Mistakes
Get link
Facebook
X
Pinterest
Email
Other Apps
-
Updated: 8 October 2026 |
Author: Samson Ese | Daily Reality NG
Payroll Software Nigeria 2026: Stop FIRS Mistakes With These Tools
Editorial and accuracy note: This guide uses the 2025 Nigerian tax legislation that took effect in 2026, official government material, and current public information from payroll providers. Software capabilities and commercial terms can change. Where a feature or price is a provider claim, it is treated as a provider claim rather than independent proof. This is an editorial comparison, not legal, tax or accounting advice for a particular business.
Payroll software is no longer simply a faster way to produce payslips. For a Nigerian business in 2026, the payroll system has to cope with a new personal-income-tax framework, employee deductions, employer contributions, state-level tax administration, annual employer returns, payment records and an audit trail that someone can actually understand months later.
That is why the real question is not simply, “Which payroll software is cheapest?”
The better question is: Which payroll system reduces the number of ways my business can calculate, approve, pay, record or report something incorrectly?
There is an important correction to the title of this article before we go further. Many Nigerian business owners still use “FIRS” as shorthand for tax compliance. Since the 2025 tax reforms, the federal revenue institution is the Nigeria Revenue Service (NRS), while PAYE for ordinary employees is administered through the relevant tax authority, generally the State Internal Revenue Service for the state concerned. A payroll platform that says it is “FIRS compliant” should therefore be questioned about exactly which tax obligation, authority and filing process it supports.
The distinction matters because a company can calculate an employee's PAYE correctly and still have a compliance problem if it sends the money to the wrong authority, misses a required filing, carries an outdated employee record, uses the wrong tax rules or cannot produce evidence of what happened.
The 2026 reality: The Nigeria Tax Act 2025 introduced a new individual tax-rate schedule from 1 January 2026. The first ₦800,000 of taxable income is taxed at 0%, followed by bands of 15%, 18%, 21%, 23% and 25%. The Nigeria Tax Administration Act 2025 also requires employers to submit an annual return for employee emoluments by 31 January for the preceding year. Your payroll system therefore has to be built around the current rules rather than an old spreadsheet formula.
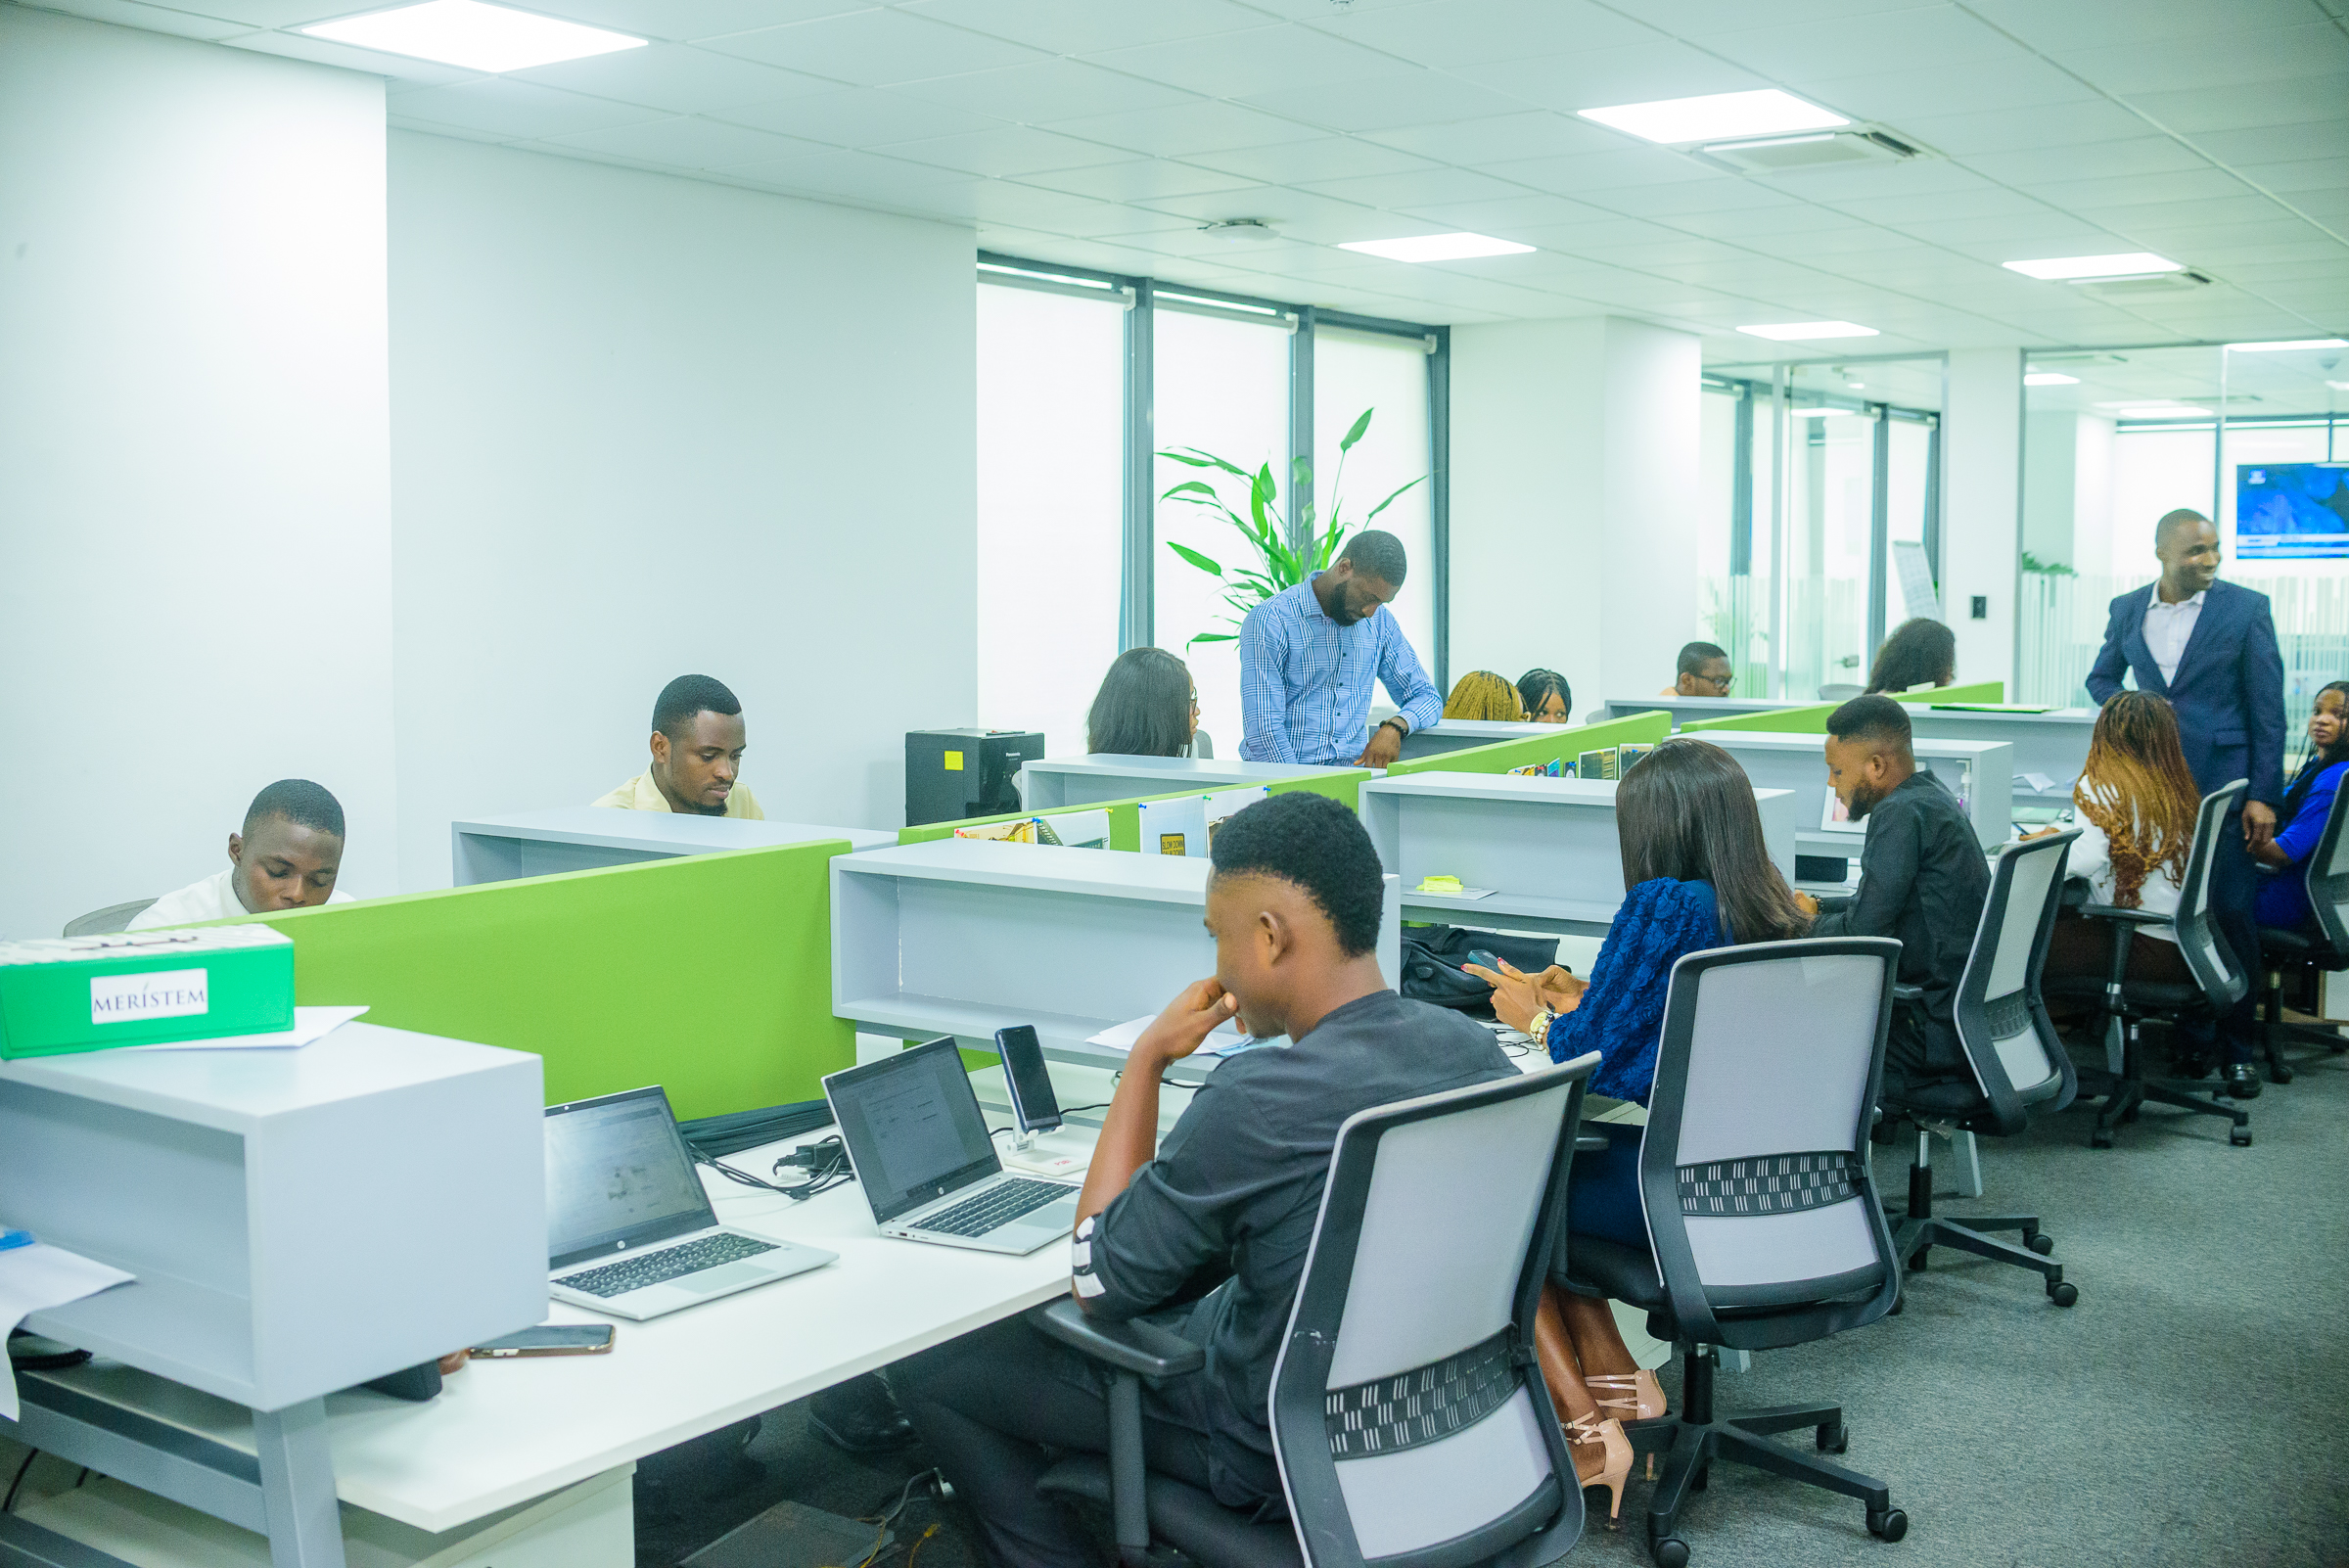
Nigerian digital work environment: payroll technology ultimately serves real employees, managers and finance teams.
What this guide covers
What changed for Nigerian payroll in 2026.
Why manual payroll creates more than calculation risk.
What payroll software should actually automate.
How PAYE, pension and other payroll obligations fit together.
Five payroll platforms worth investigating in Nigeria.
How to compare software without trusting marketing promises.
What small businesses should buy versus what larger employers need.
A practical payroll software selection scorecard.
A 30-day implementation and verification plan.
15 frequently asked questions.
1. The biggest Nigerian payroll mistake in 2026 is not necessarily a bad formula
A spreadsheet can calculate a number perfectly and still produce a bad payroll process.
Imagine a business with 14 employees. The finance officer has a workbook containing salary, housing allowance, transport allowance, pension, PAYE and net pay. Every month, the officer copies the previous month's sheet, changes the salary figures, adds new employees and removes staff who have left.
Nothing appears unusual.
Then one employee receives a different allowance. Another submits a rent declaration. A third joins halfway through the month. A fourth leaves before payday. Someone changes a formula while inserting a row. The person responsible for the payroll goes on leave. The company opens a second location in another state.
Suddenly the risk is not “Can Excel multiply correctly?”
The risk is whether the entire payroll chain still produces a traceable and defensible result.
Good payroll software attacks that problem by creating controls around the calculation. It should help establish who entered a change, what changed, which calculation was produced, who approved it, which employees were paid, what statutory amounts were generated and what records remain available afterward.
That is a much more useful definition of payroll automation than simply pressing a “Calculate” button.
2. What actually changed for Nigerian payroll in 2026?
The 2025 tax legislation took effect from 1 January 2026. The Nigeria Tax Act replaced the previous personal-income-tax framework and introduced a new schedule for individual income tax.
The statutory rates are:
Annual taxable income band
Rate
What it means
First ₦800,000
0%
No tax is charged on this first band of taxable income.
Next ₦2.2 million
15%
The marginal rate applies only to income falling in this band.
Next ₦9 million
18%
The next slice is taxed at the higher marginal rate.
Next ₦13 million
21%
This band applies after the previous bands have been exhausted.
Next ₦25 million
23%
Higher-income taxable amounts move into this band.
Above ₦50 million
25%
Only the portion above ₦50 million falls into the highest band.
The most important operational lesson is that payroll software should not apply one percentage to an employee's entire salary. The calculation is progressive, and the amount subject to tax depends on the employee's taxable income after relevant reliefs and deductions.
The new framework also changed the information employers need to manage. For example, rent relief is now part of the tax calculation framework, so a payroll process may need to collect and retain an employee's relevant declaration or supporting information rather than simply applying an old consolidated-relief formula.
This is precisely where a static spreadsheet becomes dangerous. The formula may look familiar while the law behind the formula has changed.
The 2026 payroll lesson
Do not ask only whether your payroll software calculates PAYE.
Ask whether the software:
uses the current 2026 tax rules;
records the assumptions behind each calculation;
handles changes to employee compensation;
produces a reviewable payroll report;
supports the relevant state tax process;
keeps employee and payroll records together;
supports statutory reporting;
allows authorised people to approve changes;
preserves records after payroll is closed; and
makes it easy to reconcile payroll against actual bank payments.
3. Why “FIRS compliance” is too vague for a payroll buyer
Search for Nigerian payroll software and you will see the phrase “FIRS compliant” repeatedly. Treat that phrase as a starting point, not as proof.
A business owner should immediately ask: Compliant with which obligation?
PAYE is personal income tax collected through employers. The relevant authority depends on the tax jurisdiction. The Nigeria Tax Administration Act establishes the role of State Internal Revenue Services in the administration of individual income tax and PAYE. That means a Lagos employee's PAYE process is not automatically the same operational process as one involving an employee in Rivers, Kano, Kaduna or another state.
The federal tax administration framework still matters enormously to Nigerian businesses, especially where federal taxes and reporting obligations apply. But it is inaccurate to tell every employer that PAYE simply means “pay FIRS.”
This distinction is one of the strongest tests you can use when evaluating payroll vendors.
Ask the vendor these six questions
Which tax authority receives the PAYE for employees in each Nigerian state?
How does your software determine the employee's relevant tax jurisdiction?
Which 2026 tax rules are currently built into the calculation engine?
Can I see a sample calculation before buying?
Does the software calculate the obligation, prepare the filing, submit it, or all three?
What evidence remains after a remittance or filing is completed?
If the salesperson answers “the software handles everything,” ask them to demonstrate the exact workflow. Payroll is too important to leave at the level of a slogan.
4. What manual payroll gets wrong most often
Manual payroll is not automatically bad. A very small business with two employees can maintain a carefully controlled spreadsheet and produce accurate results.
The problem is that manual systems become fragile as the number of variables grows.
1. Old tax formulas survive after the law changes
This is one of the clearest 2026 risks. A workbook created under the old tax structure can continue producing apparently reasonable numbers even after the underlying legislation changes.
A new payroll engine should make the current rule set explicit rather than hiding the calculation inside an inherited spreadsheet.
2. Employee changes are entered inconsistently
One person updates salary. Another updates allowances. A third person handles pension. Someone else prepares the bank payment file. Without controlled workflows, the same employee can have different information in different records.
3. Leavers remain active
A resigned employee who remains in the payroll file for one extra cycle is not merely an HR mistake. It can become a payment, reconciliation and recordkeeping problem.
4. New employees are entered late
A new employee can be paid correctly while still having incomplete statutory records. Payroll software should make missing information visible before the payroll is approved.
5. One-off payments disappear into the spreadsheet
Bonuses, allowances, commissions, reimbursements and adjustments can produce tax consequences or change the gross-to-net calculation. A good system should identify the reason for the change rather than simply showing that the final number is different.
6. Payroll and bank records do not match
A payroll report might show ₦8.4 million in net salary while the bank statement contains several transfers totalling a different amount. Someone then has to investigate manually.
Reconciliation is not a luxury. It is part of a defensible payroll process.
A structured payroll system should fit into the wider HR and finance process rather than operate as an isolated spreadsheet.
5. What payroll software should automate in Nigeria
The best system is not necessarily the one with the longest feature list. It is the one that automates the repetitive work while leaving meaningful decisions under human control.
Employee records
The system should provide one authoritative employee record containing the information required to calculate pay and maintain statutory records.
Gross-to-net calculation
The software should show how gross earnings become taxable income, deductions and net pay. A black-box number is less useful than a calculation that a payroll officer can inspect.
Tax-rule updates
This is particularly important in 2026. Ask the vendor how tax-law updates are deployed. Do not assume “cloud software” automatically means “current law.”
Payroll approvals
A business should be able to separate payroll preparation from payroll approval where appropriate. That reduces the risk of one person changing employee data and releasing payment without independent review.
Payslips
Employees should receive understandable payslips showing gross pay, deductions and net pay. A clear payslip reduces disputes because employees can see what changed.
Statutory reports
Payroll software should make the relevant statutory schedules and supporting records easier to prepare and reconcile.
Audit history
If an employee's salary changes from ₦300,000 to ₦360,000, the system should make it possible to understand who made the change, when it happened and why.
Reconciliation
The payroll result should be compared with the amount actually paid and the amounts subsequently remitted. The software does not eliminate the need for review; it makes review more systematic.
6. The five payroll platforms Nigerian businesses should investigate in 2026
There is no universal winner. A five-person Nigerian startup, a 500-person company and an African employer with workers in several countries have very different requirements.
The following shortlist is based on publicly available product information. The descriptions are not endorsements, and provider claims are not treated as independent proof.
1. PaidHR — strong local HR and payroll focus
PaidHR positions itself as an HR and payroll platform with employee payroll, statutory-remittance workflows, benefits and broader people-operations features. Its public product information describes payroll calculations, payslips, payroll API capabilities, employee pension and payroll-tax processes.
The strongest reason to investigate PaidHR is not simply its payroll calculator. It is the broader workflow around employee records and statutory obligations.
That can be valuable for a growing Nigerian company that has outgrown a spreadsheet but does not want payroll sitting separately from HR administration.
Best fit: SMEs and growing organisations wanting payroll plus broader HR workflows.
Ask before buying: Which statutory payments does the platform actually submit on the employer's behalf, which ones does it merely calculate, and what evidence is returned after submission?
2. SeamlessHR — enterprise HR and payroll
SeamlessHR offers payroll as part of a broader HR platform and specifically markets its solution to Nigerian and African organisations. Its public product information describes payroll calculation, compliance features, salary disbursement and integration with wider employee-management functions.
Its strongest case is therefore not “cheap payroll.” It is the integration of payroll with HR processes such as recruitment, employee records, time management and performance.
For a large organisation, that integration can matter more than the cost of a simple payroll calculator.
Best fit: Larger organisations that need a broader HRIS around payroll.
Ask before buying: What implementation work is required, what modules are included in the quote, how payroll changes are controlled, and how the system handles employees across different Nigerian tax jurisdictions?
3. Workpay — useful for African and multi-country teams
Workpay positions its platform around payroll, HR and employer-of-record services across Africa. Its public Nigeria-facing materials describe payroll management, payslips, employee self-service, automated calculations, statutory reporting and salary disbursement.
This makes it particularly relevant to a Nigerian company that expects to employ people across more than one African country.
Its published pricing also separates payroll and HR from outsourced payroll and EOR services, so the buyer needs to identify which service is actually required rather than comparing an EOR price with ordinary payroll software.
Best fit: Businesses managing African or international teams.
Ask before buying: Are you buying software, outsourced payroll, EOR services or a combination? The compliance responsibility and cost structure can be very different.
Salario presents itself as a Nigerian payroll and workforce platform covering employee data, compensation, approvals, compliance, payment and accounting. Its public tools include a Nigeria PAYE calculator and employer-cost calculator.
That focus can be useful for a small or medium Nigerian business that wants a more local payroll experience rather than a global HR system with Nigerian functionality added to it.
However, a buyer should still verify current commercial terms and exactly which filing or remittance functions are performed by the platform.
Best fit: Nigerian SMEs seeking payroll and workforce-management functions in one system.
Ask before buying: Which state-level PAYE workflows are supported, how statutory reports are generated, and whether payment is actually made by the platform or merely prepared for the employer.
5. Kua — attractive for small-team payroll economics
Kua's Nigeria product combines payroll, employee records and company-money functions. Its current public Nigeria pricing states a 1% company-wallet funding fee and no separate standard subscription fee for that funding model.
That pricing structure is fundamentally different from a conventional per-employee subscription. It can therefore be attractive to a small company that wants to avoid paying a fixed payroll fee for months when it has little or no payroll activity.
But pricing should never be the first selection criterion. The buyer still needs to test the tax calculation, statutory reporting, approval process, record retention and payment workflow.
Best fit: Small businesses, startups and operators who value a simple payroll-and-money workflow.
Ask before buying: What happens when the business grows, what records remain available for audit, and which statutory obligations are calculated versus actually paid through the platform?
7. Payroll software comparison: what matters more than “best”
Current plan limits, statutory reporting and remittance workflow
Public information available; verify current terms
Kua
Small teams and flexible payroll funding
1% funding economics, payment workflow, scaling
Public Nigeria pricing
Notice what is missing from this table: a meaningless “winner” column.
A payroll platform is infrastructure. The right product depends on the business's employee count, jurisdictions, approval structure, accounting setup, salary-payment method and internal compliance capability.
8. How to test whether payroll software actually works
Do not buy payroll software because the dashboard looks modern.
Before signing a contract, create a test payroll containing several deliberately different employees.
Test employee A: straightforward salary
Give the system a normal monthly salary and verify the gross-to-net calculation against an independent calculation using the current 2026 tax framework.
Test employee B: salary plus rent relief
Enter a legitimate rent-relief scenario and determine exactly how the software handles the declaration, calculation and supporting documentation.
Test employee C: new starter
Add an employee who begins partway through a payroll cycle. Check how the software prorates earnings and whether statutory calculations remain correct.
Test employee D: leaver
Terminate an employee before the next payroll. Check whether the system prevents an accidental future payment.
Test employee E: variable compensation
Add a bonus or commission. Check whether the payroll calculation shows the effect clearly rather than silently changing the final net amount.
Test employee F: different tax jurisdiction
If your staff live or work across states, test how the platform identifies the relevant tax authority and produces the corresponding records.
Then break the system
A serious payroll demonstration should not only show the happy path.
Ask the vendor to demonstrate what happens when:
a bank payment fails;
an employee's salary is changed after payroll preparation;
a statutory report is regenerated;
a payroll run is cancelled;
a user without approval rights attempts to release payroll;
an employee record is corrected after a previous payroll;
the tax rules change; and
the company needs historical payroll records two years later.
The answers tell you much more about the quality of the system than a sales presentation does.
9. A practical 100-point payroll software scorecard
Here is a Daily Reality NG decision framework you can use before selecting a platform.
Category
Points
What earns the points?
2026 tax accuracy
20
Current rules, transparent calculations and update process.
Statutory workflow
15
Clear reports, deadlines and defined remittance responsibility.
Audit trail
10
Changes, approvals and historical payroll records are traceable.
Employee records
10
One controlled source of payroll information.
Payroll approval
10
Separation of preparation and approval where required.
Reconciliation
10
Payroll, bank and statutory amounts can be reconciled.
Security and access
10
Role-based access, controlled permissions and secure records.
Employee self-service
5
Payslips and relevant employee information are accessible.
Integrations
5
Useful accounting, attendance or payment integrations.
Cost transparency
5
Clear pricing and predictable additional charges.
I would not automatically reject a platform scoring below 80. I would reject a platform that scores poorly on tax accuracy, statutory workflow, audit trail or security, even if its overall feature count is impressive.
A payroll product can have beautiful HR dashboards and still be the wrong system for your business if the calculation and compliance controls are weak.
10. The hidden cost calculation Nigerian business owners should perform
Software price is only one part of payroll cost.
Suppose a 20-person company spends ₦80,000 per month on payroll administration, including finance time, reconciliation, corrections and outsourced support. A software platform costing ₦40,000 per month may actually reduce total operating cost even though the software itself is not free.
Conversely, a “free” platform can be expensive if it creates extra manual work, requires employees to use an unfamiliar payment method, or leaves the finance team manually preparing statutory reports.
Use this model:
Total payroll operating cost = software fees + payroll staff time + correction time + reconciliation time + payment costs + compliance support + cost of avoidable errors.
You do not need to assign a perfect naira value to every variable. Even a rough estimate can reveal whether the software is genuinely cheaper.
Example
Assume a business spends:
₦35,000 monthly on payroll software;
₦50,000 worth of staff time managing payroll;
₦20,000 equivalent staff time reconciling payroll;
₦15,000 average monthly cost of correcting avoidable payroll errors.
The operational cost is approximately ₦120,000 per month.
If a different platform costs ₦60,000 but reduces the manual workload and correction burden materially, it may be cheaper in practice.
That is why comparing “₦1,500 per employee” against “₦1,000 per employee” without looking at the entire workflow is weak decision-making.
A payroll system should connect HR, finance and compliance rather than leaving each team with a separate version of the truth.
11. PAYE is not the only payroll obligation
A business owner who asks only, “Does this software calculate PAYE?” is asking too narrow a question.
Depending on the business and workforce, payroll can involve pension contributions, statutory insurance-related obligations, training-related obligations, housing-fund arrangements, employee benefits, tax deductions and other employer responsibilities.
Not every obligation applies to every employer in exactly the same way. That is another reason a payroll platform should expose its calculation assumptions instead of hiding everything behind one “compliant” label.
The buyer should build an obligation map before implementation.
Area
Question to answer
Payroll-system requirement
PAYE
Which authority applies to each employee?
Correct jurisdiction and current tax calculation.
Pension
Which employees are covered and what is the contribution base?
Controlled contribution calculation and records.
NHF
Does the employee's circumstances require or support a deduction?
Explicit employee status and deduction record.
NSITF / related employer obligations
Does the employer have an obligation and what is the calculation basis?
Employer-side reporting and reconciliation.
ITF
Does the business fall within the relevant threshold?
Separate employer liability tracking.
Benefits and allowances
How are taxable and non-taxable components treated?
Clear pay-item classification.
Annual returns
Can the system produce the required annual employee information?
Year-end reporting and historical records.
12. The 31 January problem many employers underestimate
Monthly payroll work and annual employer returns are not the same thing.
Under section 14 of the Nigeria Tax Administration Act 2025, an employer is required to file a return with the relevant tax authority for employee emoluments paid during the preceding year, not later than 31 January.
The return must disclose information including gross emoluments, allowances and benefits in kind, deductions, net emoluments and tax deducted.
This is why payroll records should not be treated as disposable monthly calculations.
If the January return becomes a frantic exercise of opening 12 spreadsheets, checking bank statements and asking employees what happened during the previous year, the payroll process was not designed correctly.
Do not confuse annual PAYE reporting with simply paying PAYE every month.
Monthly deductions and remittances do not eliminate the need to maintain accurate annual employee records and complete the applicable annual reporting process.
13. What penalties teach us about payroll software
The point of a payroll system is not to “avoid FIRS penalties” through a magic compliance button.
The point is to reduce the probability of preventable failures.
Under the Nigeria Tax Administration Act framework, failure to deduct tax where required can expose the responsible party to significant administrative consequences, while tax deducted but not remitted can attract the underlying amount plus penalties and interest.
That distinction is important.
If an employer calculates ₦300,000 PAYE, deducts it from employees and then fails to remit it, the software cannot honestly be described as having “prevented the tax problem” merely because it produced the right ₦300,000 figure.
The business still needs a payment and filing control.
This is why the strongest payroll systems combine:
calculation;
approval;
payment preparation;
statutory reporting;
deadline reminders;
reconciliation; and
historical evidence.
14. A Nigerian payroll control system that works even when the internet or staff availability does not
Payroll technology is only one part of the control environment.
Nigerian businesses should also design a fallback process for power interruptions, connectivity problems, bank downtime, unavailable staff and failed payment instructions.
A practical process is:
Close employee changes: establish a fixed cut-off before payroll day.
Run payroll: generate gross-to-net results.
Review exceptions: investigate unusually large changes.
Approve payroll: an authorised person confirms the final run.
Export records: preserve the payroll report and payment schedule.
Pay employees: use a traceable payment process.
Reconcile: compare payroll totals against actual bank payments.
Remit statutory amounts: follow each applicable deadline.
Save evidence: retain confirmations and reports.
Lock the period: prevent silent changes to closed payroll.
A system that cannot support this sequence may still calculate salaries, but it is not providing the level of control a growing employer needs.
15. How to avoid choosing payroll software based on marketing
Payroll vendors naturally describe their products in the strongest possible terms. That is normal commercial behaviour.
Your job as the buyer is to translate every marketing statement into a testable question.
Marketing statement
Better question
“100% compliant”
Which laws, authorities and obligations are covered, and what remains my responsibility?
“Automated tax filing”
Does the platform actually submit the return and payment, or only prepare the data?
“Real-time payroll”
What happens if a calculation changes after approval?
“AI-powered payroll”
Which payroll decision does the AI make, and what human approval is required?
“Error-free”
What validation controls detect bad employee data or unusual calculations?
“Affordable”
What will I pay at my current headcount and at twice my current headcount?
“Nigeria-ready”
Show me the 2026 calculation for a realistic Nigerian employee.
16. The two-person business does not need the same system as a 2,000-person company
For 1–5 employees
Keep the process simple. The most important requirements are accurate 2026 calculations, reliable employee records, payslips, clear statutory schedules and a repeatable monthly routine.
A full enterprise HRIS may be unnecessary at this stage.
For 6–30 employees
Approval controls and employee self-service become more useful. At this point, the founder should stop being the only person who knows how payroll works.
For 31–100 employees
Integration becomes increasingly valuable. Attendance, leave, employee changes, payroll and accounting should not require repeated manual re-entry.
For 100–500 employees
Audit trails, role-based access, approval workflows, reporting and reconciliation should be treated as core requirements.
For 500+ employees
The implementation itself becomes a major project. Data migration, employee communication, access controls, integrations, statutory reporting, historical records and testing should all be planned before the first production payroll.
17. A 30-day payroll software implementation plan
Days 1–5: clean the employee data
Remove former employees.
Check duplicate records.
Confirm salary structures.
Confirm bank information.
Confirm pension information where applicable.
Identify employees with missing tax information.
Document relevant allowances and benefits.
Days 6–10: build the payroll rules
Configure the 2026 PAYE framework.
Configure pension assumptions.
Configure applicable employer obligations.
Configure pay items.
Configure approval roles.
Configure payroll cut-off dates.
Days 11–15: run parallel payroll
Do not immediately abandon the old process.
Run the new software alongside the existing calculation and compare employee by employee.
Investigate every difference.
Days 16–20: test exceptions
Add a new employee, remove an employee, change salary, add a bonus, correct a deduction and produce the statutory reports.
Days 21–25: test payment and reconciliation
Compare the approved payroll total with the payment file. Simulate a failed payment. Check what evidence is produced.
Days 26–30: go live with a controlled first run
Keep the payroll approval process deliberately cautious during the first few cycles. Review exceptions before releasing the payment.
Do not measure implementation success by how quickly the software is switched on.
Measure it by whether the business can explain every significant payroll number after the first three production cycles.
18. The payroll audit checklist Nigerian businesses should keep
Every active employee has one controlled payroll record.
Former employees are removed or correctly marked inactive.
Salary changes have an approval trail.
Variable pay has a documented reason.
The 2026 PAYE calculation has been independently tested.
Relevant employee relief information is documented.
Pension calculations are checked against the applicable basis.
Employer statutory obligations are tracked separately from employee deductions.
Payroll is approved before payment.
Bank payments reconcile to the approved payroll.
Statutory remittances reconcile to payroll deductions.
Annual employee returns can be produced from the system.
Payroll records can be retrieved for previous periods.
Access is restricted according to job responsibility.
The business knows exactly who is responsible for each compliance step.
19. What payroll software cannot fix
Automation does not eliminate bad management.
If employee information is wrong, software can automate the wrong information.
If the salary structure is poorly designed, software can calculate it perfectly.
If the employer selects the wrong tax jurisdiction, a system can faithfully produce the wrong workflow.
If the company ignores an alert, software cannot force a human being to act.
If a manager approves an incorrect bonus, the software may simply process it.
Therefore the real model is:
Good payroll = accurate rules + accurate employee data + controlled approvals + timely payments + correct remittances + preserved evidence + human review.
Software strengthens this chain. It does not replace the chain.
20. Which payroll software should you choose?
If you are a very small Nigerian business, prioritise simplicity, current tax calculations, clear statutory reports and low administrative overhead.
If you are a growing SME, look closely at approval workflows, employee self-service, reconciliation and integrations.
If you operate across several African countries, Workpay's broader regional model may deserve investigation.
If your business needs a large HR platform around payroll, SeamlessHR deserves an enterprise-focused evaluation.
If you want local HR and payroll workflows, PaidHR is worth comparing closely.
If your priority is a Nigerian-focused payroll platform, Salario is worth testing against your actual payroll.
If you are a small operator who values a simple payroll and company-money workflow, Kua's current pricing model may be attractive.
But I would not choose any of them without running the same test payroll through the shortlisted platforms.
The winning system is the one that produces the correct result, explains how it got there, gives your team proper controls and leaves enough evidence for someone else to understand the payroll later.
21. My decision rule for Nigerian business owners
Use this five-question filter before paying for payroll software:
Does it use the current Nigerian tax rules?
Does it correctly identify the relevant tax authority?
Can I see and independently verify the calculation?
Can my finance team reconcile payroll, payments and statutory remittances?
Will the records still make sense if an auditor or tax officer asks questions later?
If a platform fails one of those questions, do not let a beautiful dashboard compensate for it.
22. Final verdict
Nigerian payroll in 2026 is a different problem from the spreadsheet problem many businesses solved several years ago.
The new tax framework changed the calculation environment. Employer reporting requirements make historical payroll records important. State-level administration means businesses with employees in different jurisdictions need to understand where PAYE belongs. Growing companies also need to coordinate HR, finance, payment and compliance data.
That is why payroll software should be judged as a control system, not merely a calculator.
The title of this article uses “FIRS mistakes” because that is the language many Nigerian business owners use when searching for tax-compliance help. But the technically correct 2026 approach is broader: understand the Nigeria Revenue Service framework, identify the relevant state tax authority for PAYE, apply the current Nigeria Tax Act, maintain the required records and make sure every remittance and return can be reconciled.
The biggest mistake is not using Excel.
The biggest mistake is using any payroll process that nobody can independently verify.
If your current payroll is still a spreadsheet, do not panic and replace it tomorrow simply because software exists. First document your present process, run a test calculation under the 2026 rules, identify the points where errors can enter, then compare software against those specific weaknesses.
That is how a Nigerian business turns payroll automation from a convenience into a genuine control improvement.
Samson Ese | Founder, Publisher & Editor-in-Chief, Daily Reality NG
I research Nigerian financial, business, technology, legal and everyday systems with a focus on what the rules mean in practice. For this payroll guide, I separated statutory requirements from software-provider claims and focused on the controls a Nigerian employer should test before trusting a payroll system.
This article is a document-based editorial analysis. It is not a hands-on laboratory test of the listed payroll platforms, and it does not represent a personal claim that I used each service.
Before choosing a payroll platform:
Run one realistic employee calculation through at least two shortlisted systems, compare the result against an independent calculation, then ask each vendor to demonstrate the filing, remittance, approval and reconciliation workflow.
Do not buy based on “100% compliant” marketing alone. Buy the system whose controls you can understand and verify.
Frequently Asked Questions
1. What is the best payroll software in Nigeria in 2026?
There is no single best platform for every Nigerian employer. PaidHR, SeamlessHR, Workpay, Salario and Kua serve different operating models. The best choice depends on employee count, HR requirements, tax jurisdictions, payment workflow, integrations, reporting needs and budget. Test the actual payroll calculation and statutory workflow before deciding.
2. Does Nigerian payroll software automatically pay FIRS?
Do not assume that from the phrase “automated payroll.” PAYE generally involves the relevant tax authority for the employee's jurisdiction, while federal taxes and other obligations can involve the Nigeria Revenue Service. Some platforms calculate amounts, some prepare reports, some support remittance workflows and some offer outsourced services. Ask the provider exactly what it submits and what remains your responsibility.
3. What changed in Nigerian PAYE in 2026?
The Nigeria Tax Act 2025 introduced a new individual tax-rate schedule effective from 1 January 2026. The bands begin with 0% on the first ₦800,000 of taxable income, followed by 15%, 18%, 21%, 23% and 25% bands. Payroll systems using an old formula need to be checked.
4. Is PAYE paid to FIRS or the State Internal Revenue Service?
PAYE is generally administered by the relevant state tax authority for ordinary employees, although the exact jurisdiction can depend on the employee's circumstances. The 2026 tax framework makes it important to determine the correct authority rather than assuming every PAYE payment goes to the federal revenue service.
5. What is the 2026 PAYE tax rate in Nigeria?
The statutory individual schedule is progressive: first ₦800,000 at 0%; next ₦2.2 million at 15%; next ₦9 million at 18%; next ₦13 million at 21%; next ₦25 million at 23%; and amounts above ₦50 million at 25%. The actual PAYE calculation depends on taxable income and applicable deductions or reliefs.
6. Can a small Nigerian business use Excel for payroll?
Yes. Software is not automatically a legal requirement. A small business can maintain a controlled spreadsheet if it can calculate correctly, preserve records, manage employee changes, meet deadlines and reconcile payments and statutory obligations. The problem is that spreadsheets become increasingly fragile as complexity grows.
7. How many employees justify payroll software?
There is no universal employee threshold. Even a five-person company can benefit if payroll changes frequently or the founder lacks time for administration. A better test is complexity: multiple allowances, different states, variable pay, several approvers, pension administration, employee self-service and reconciliation requirements all increase the value of dedicated software.
8. Does payroll software eliminate tax penalties?
No. Software reduces certain manual risks but cannot guarantee compliance. A business can still enter incorrect employee information, approve a wrong calculation, fail to fund a payment or ignore a deadline. The strongest systems create controls that make these failures easier to detect and prevent.
9. What should a payroll payslip contain?
A useful payslip should clearly identify the employee and pay period and show gross earnings, relevant deductions, statutory deductions and net pay. The exact format can depend on the employer's payroll process and applicable requirements. The important principle is that the employee should be able to understand how the final amount was reached.
10. Should I choose payroll software based on price?
No. Price matters, but total operating cost matters more. Compare software fees with the time required for payroll, reconciliation, corrections, reporting and employee support. Also calculate what the platform will cost if your headcount doubles.
11. What is the biggest payroll mistake Nigerian SMEs make?
One major risk is continuing to use an old payroll formula after tax rules change. Other common weaknesses include incomplete employee records, poor approval controls, incorrect jurisdiction handling, failure to reconcile payments and treating monthly payroll calculations as if they replace annual reporting obligations.
12. Can payroll software handle employees in different Nigerian states?
Some platforms are designed to handle multi-jurisdiction payroll, but the exact capability must be tested. Ask the provider to demonstrate how it identifies the relevant tax authority, calculates the employee's PAYE and produces the necessary records for each jurisdiction.
13. Should payroll software calculate pension too?
A serious Nigerian payroll platform should be able to support the applicable pension calculations and records where the employer and employees are covered. The business should still verify the contribution basis and reconcile the software output against the relevant pension records.
14. How do I know whether a payroll provider's compliance claim is genuine?
Ask for a demonstration using your own realistic employee scenario. Request the calculation, report, approval process, remittance workflow and evidence produced after submission. Also ask which parts are automated and which parts remain your responsibility. A specific demonstration is more useful than a general compliance promise.
15. What should I do before switching payroll software?
Clean employee records, document the current payroll process, identify all statutory obligations, test the new software against independent calculations, run at least one parallel payroll, reconcile the results and establish an approval process before going live. Keep historical payroll records accessible after migration.
Primary and Provider Sources Used for Verification
The following resources were used to verify the statutory framework and the current public descriptions of selected payroll products. Provider pages describe their own products and are not treated as independent proof of legal compliance.
Last editorial verification: 8 October 2026. Tax rules, filing procedures, software capabilities and commercial terms can change. The relevant government authority and the provider's current documentation should be checked again before a consequential filing, payment or procurement decision.




Comments
Post a Comment